Winter
Ice dams, frozen and burst pipes, snow-load collapse and ice storms.
- Late-January 2019 polar vortex
- February 2023 southeast ice storm
- December 2013 mid-Michigan ice storm
Both peninsulas · All 83 counties
Hail on the roof, a basement full of sewer water, ice dams through the ceiling. When your carrier accepts the claim but won’t pay what the repair really costs, Michigan Insurance Appraiser gives you an independent number and an appraiser to stand behind it.
Who we are
Most Michigan homeowners and business owners never think about the appraisal clause until a claim goes sideways. The carrier agrees the loss is covered, then sends an estimate that won’t rebuild the roof or dry out the basement. That gap is where Michigan Insurance Appraiser works.
Every Michigan Insurance Appraiser file starts the same way: a free conversation about what happened, what the carrier paid and what you think it missed.
Services
From one estimate review to full panel representation, each service is built around a defensible valuation of a Michigan loss.
We serve as your appraiser after an appraisal demand under Michigan’s statutory process for disputed loss amounts.
How representation works
Independent appraisal for Michigan homeowners whose insurer underpaid a roof, water, fire or storm claim.
Appraisal for Michigan businesses, multifamily owners, condo associations and HOAs with disputed property losses.
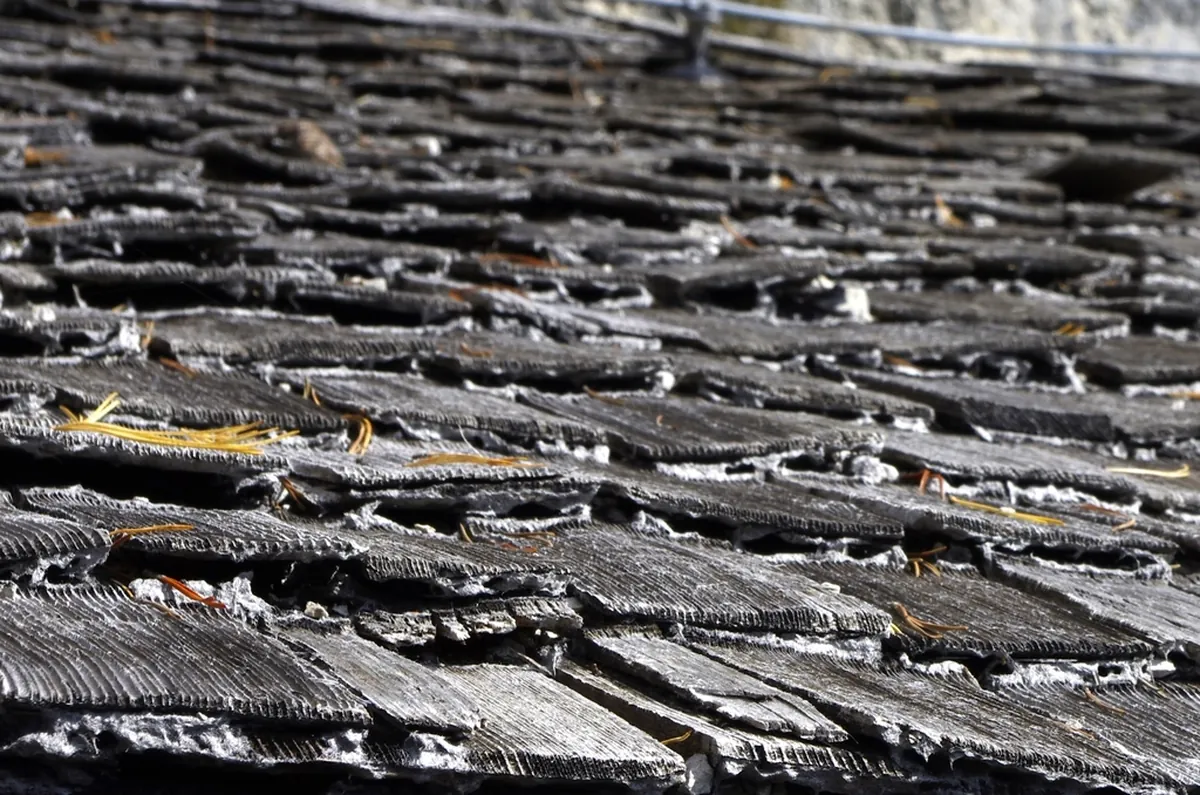
Appraisal for Michigan hail and roof claims, from bruised shingles and dented metal to repair-versus-replace disputes.
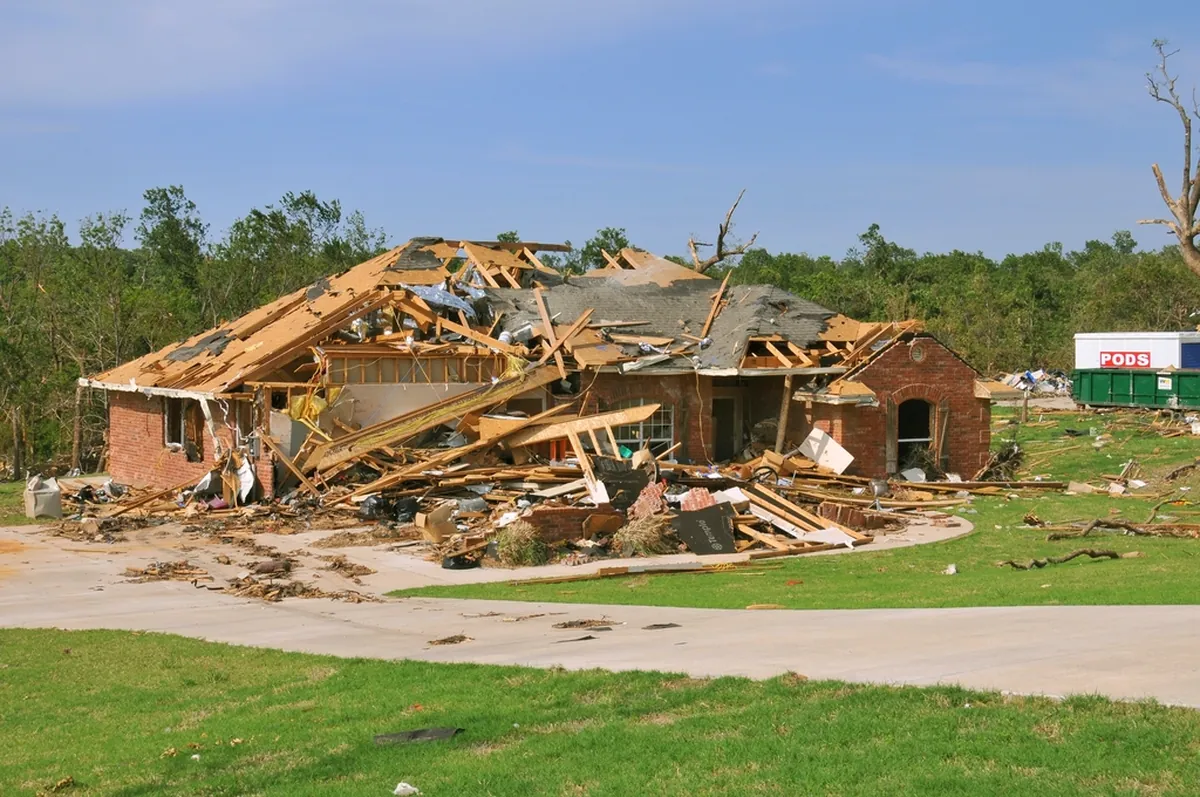
Appraisal for Michigan windstorm, derecho and tornado claims, from creased shingles to total losses.
Appraisal for Michigan ice dam leaks and frozen pipe bursts when the insurer accepts the loss but underpays it.
Appraisal for Michigan basement water, plumbing and sewer backup claims when the scope or price is in dispute.
Appraisal for Michigan fire and smoke claims, from soot cleanup disputes to full rebuild and code upgrade costs.
Appraisal for Michigan fallen tree and ice storm claims, including roof framing, crane removal and debris limits.
Appraisal for Michigan personal property claims, challenging low pricing, heavy depreciation and missed items.
An independent line-by-line review of your insurer’s estimate so you can decide your next step with confidence.
Neutral umpire services for Michigan property insurance appraisals, by agreement of the appraisers or court appointment.
From Monroe to the Keweenaw
The same policy reads very differently in a Dearborn bungalow and a Marquette camp. A Michigan Insurance Appraiser prices each with the region in mind.
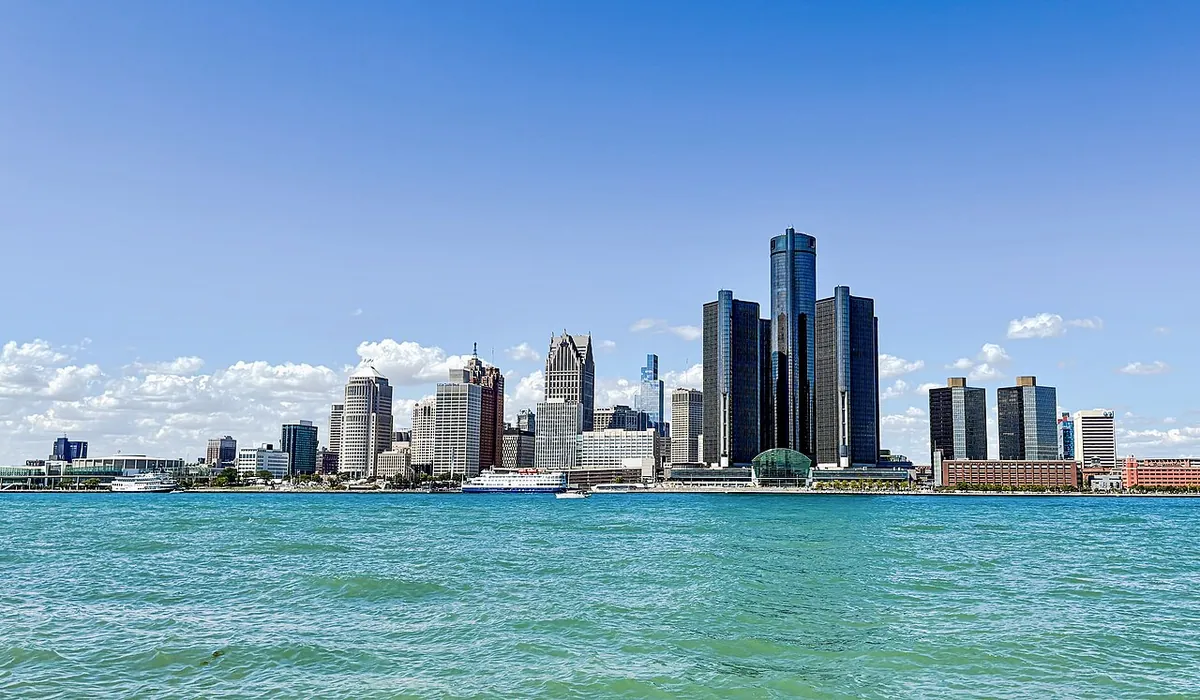
Wayne · Oakland · Macomb
Brick bungalows in Detroit and Dearborn, postwar ranches in Warren and Sterling Heights, and big colonials in Troy all share one weakness: basements. The August 2014 and June 2021 floods filled thousands of them, and the February 2023 ice storm dropped limbs across the region.
Kent · Ottawa · Kalamazoo
From Grand Rapids to the lakeshore, snow belt winters load roofs and build ice dams, and spring storms track in off Lake Michigan. The 1956 Hudsonville–Standale tornado, the 1980 Kalamazoo tornado and the 2024 Portage tornado frame the risk.
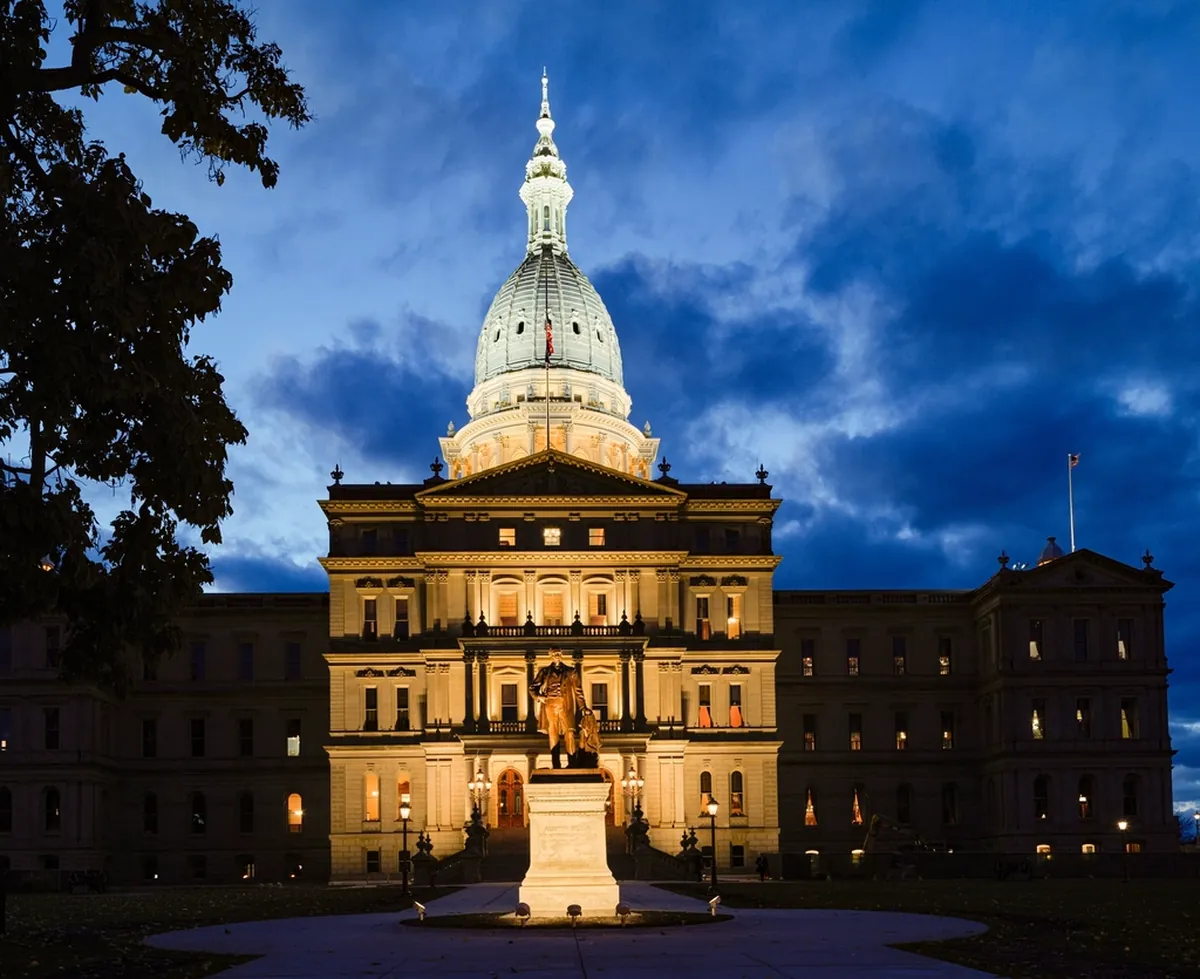
Ingham · Genesee · Saginaw
Lansing still remembers the December 2013 ice storm, Flint the 1953 Flint–Beecher tornado, and the Great Lakes Bay region the 2020 Edenville and Sanford dam failures. Housing ranges from early-1900s neighborhoods to newer suburbs.
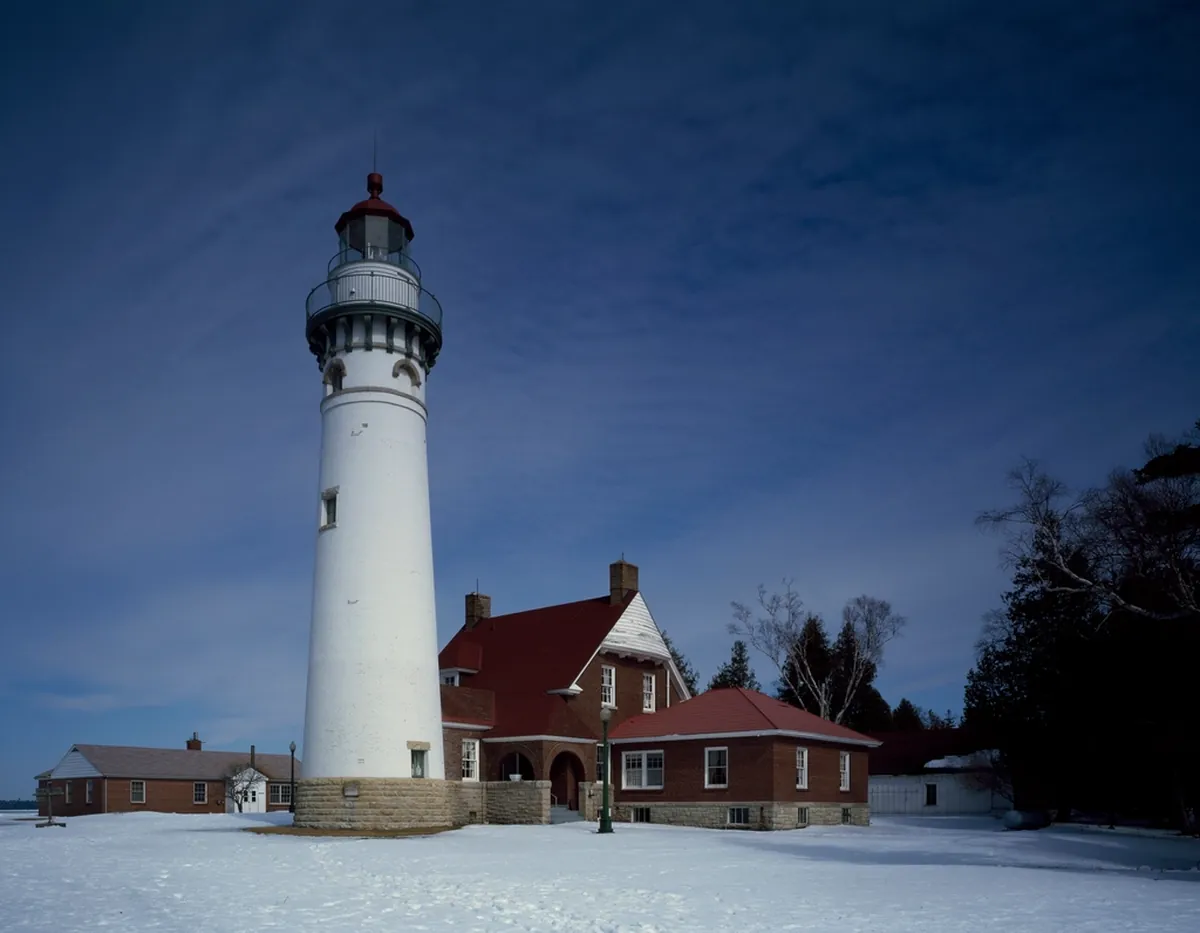
Grand Traverse · Otsego · Emmet
Cottages, condos and year-round homes around Traverse City and Gaylord face heavy snow and long freezes, and the May 2022 Gaylord tornado showed how quickly a summer storm can hit up north. Vacancy and heat conditions matter for seasonal homes.
Marquette · Houghton · Chippewa
The U.P. measures snow in feet, not inches. Older wood-frame homes, camps and commercial buildings along Lake Superior see roof collapse risk, ice dams and gales that rival the November storms of Great Lakes history.
A year of claims
Every season brings its own losses. These are the patterns a Michigan Insurance Appraiser sees most, with storms Michigan owners still talk about.
Ice dams, frozen and burst pipes, snow-load collapse and ice storms.
Hail, tornadoes and river flooding as storms build across the Lower Peninsula.
Flash floods, sewer backups, derechos and lightning fires.
Gales off the Great Lakes, fallen trees and heating-season fires.
The process
Michigan’s Insurance Code sets the basic shape: a written demand, two independent appraisers, an umpire if needed, and an award signed by any two of the three. Here is how a Michigan Insurance Appraiser moves a claim through it.
Read the full process guidePut your figure and the insurer’s figure side by side, line by line, so the dollar gap is clear. Appraisal works best when the argument is about price and quantity, not about whether the loss is covered.
Find the appraisal provision in your policy and note its exact wording, notice rules and any timing language. Michigan law requires this provision in property policies, but the details still come from your contract.
Either side can start the process with a clear written demand for appraisal sent to the insurer. Keep proof of when and how it was delivered.
You and the insurer each pick a competent, independent appraiser, generally within 20 days of the demand. Your appraiser builds and presents the valuation for your side.
The two appraisers try to agree on a neutral umpire, generally within 15 days. If they can’t agree, either side can ask a Michigan court of record to choose one.
The appraisers walk the property, review photos, invoices and estimates, and trade detailed line-item valuations. Many items settle at this stage once both sides see the same evidence.
Items the two appraisers can’t agree on go to the umpire with supporting documents. The umpire weighs each disputed item and sides with the better-supported number or sets a figure between them.
A written award signed by any two of the three sets the amount of loss. The insurer then pays under the policy terms, less the deductible and prior payments, with any holdback handled as the policy allows.
Quick check
Enter the carrier’s estimate and your own. The figures shown are illustrative defaults; replace them with yours. For fees, umpire costs and break-even, open the full claim gap and fee estimator.
Free calculators
Built from real appraisal work. Everything runs in your browser and nothing is stored.
EstimatorMeasure the gap between two estimates and see what appraisal might net after fees.
Open Calculator
Depreciate line items, see the first check and how much holdback you can recover.
OpenCalculatorConvert footprint and pitch into squares, bundles and eave ice-barrier rows.
Open Calculator
Turn a 1% or 2% deductible into dollars and compare it with a flat deductible.
Open Planner
Build a claim calendar, estimate tolling and export every date to your calendar.
Open Checklist
Ten questions that show whether your claim file is ready for appraisal.
Open Estimator
Rate ice dam risk by snow belt and attic, and size illustrative interior repairs.
OpenCities
On-site inspections statewide. These pages cover the places our files come from most, with local storm history and housing notes.
Choosing help
Each plays a different role on a Michigan claim. A Michigan Insurance Appraiser handles valuation; the others handle the rest.
| Question | Insurance appraiser | Public adjuster | Attorney |
|---|---|---|---|
| Main job | Values the loss; serves on the appraisal panel | Prepares and negotiates the whole claim for you | Advises on rights, coverage and litigation |
| Best when | Coverage is accepted; the dispute is the dollar amount | The claim is large or complex from the start | Coverage is denied or deadlines are close |
| Decides coverage? | No | No (negotiates it) | Can litigate it |
| Typical fee | Flat, hourly or percentage, agreed in writing | Usually a percentage of the claim, within state rules | Varies; often contingency or hourly |
Questions
Short answers to common questions. The full FAQ goes deeper on costs, timing and Michigan specifics.
An insurance appraiser builds an independent valuation of a covered loss and, when either side demands appraisal under the policy, serves on the panel that sets the amount of loss. We also review estimates before a dispute escalates and serve as neutral umpires.
Michigan’s Insurance Code requires property policies covering fire to include an appraisal provision, and most homeowners and commercial policies contain one. Read your own policy’s appraisal condition for the exact wording and deadlines.
Generally no. Appraisal decides the amount of loss. If the insurer denied coverage, talk with a Michigan attorney about your options.
Fees vary by claim size and complexity and may be flat, hourly or a percentage of the increase. Each side typically pays its own appraiser and splits the umpire. We put our fee in writing before any work starts.
Yes. We work in all 83 counties on both peninsulas, from Detroit and Grand Rapids to Marquette, Houghton and Sault Ste. Marie.
Neither. We provide appraisal, estimating and umpire services. If your claim needs a public adjuster or an attorney instead, we’ll tell you.
Great Lakes claim guides
What the appraisal provision in every Michigan property policy says, how it works step by step, and what it can’t do.
Three different professionals help Michigan policyholders with disputed claims. Here’s how their roles, fees and timing differ.
Why ice dam claims are so common in Michigan, where insurers push back, and how to document roof and interior damage.
Statewide, both peninsulas
A Michigan Insurance Appraiser review costs nothing and takes one phone call. Bring the estimate; we’ll bring the questions.
Get in touch
Call, text or email, or send the form. We’ll review what you have, explain where the estimates differ, and tell you honestly whether appraisal makes sense.


